difference between accrual and cash basis bookkeeping for a SaaS company
The difference between accrual and cash basis bookkeeping for a SaaS company comes down to timing: when a transaction appears in the books, not just when money moves. That distinction shapes whether a monthly profit and loss statement reflects subscription activity or a bank deposit that may cover service delivered over many months.
Key Takeaways
- Cash basis tells you when money enters your bank account, but accrual basis tells you when you actually earn subscription revenue across the months you deliver service.
- Using cash basis makes monthly profit statements swing wildly when a large annual contract lands, while accrual gives a steady view of underlying business performance.
- Accrual bookkeeping is essential for investor readiness because it properly records deferred revenue and matches income to the period service is provided.
- Your choice between cash and accrual directly impacts how you calculate metrics like monthly recurring revenue and customer acquisition cost, not just your tax return.
For a founder, the choice affects how clearly you can read revenue, expenses, cash, and obligations to customers. Here’s how each method handles a subscription and why the resulting financial statements can tell different stories.
Your SaaS Financial Story: Cash vs. Accrual Bookkeeping Explained
Why This Matters for Your Growth
Cash basis records income when payment arrives and expenses when payment is made. Accrual basis records revenue as it is earned and expenses as they are incurred, even if the related cash moves earlier or later. A SaaS company taking annual prepayments can look unusually profitable in a payment-heavy month under cash accounting, then appear to have little revenue in later months. Neither view changes the bank balance, but each answers a different question about business performance.
This difference matters when comparing monthly results, setting a budget, or explaining performance to a board or potential investor. A cash balance shows available funds; it does not show how much subscription revenue belongs to a given month or which costs relate to that revenue. Accrual reporting gives founders a period-based view, while cash tracking remains essential for managing liquidity and payment timing.
Our Approach to Evaluating Bookkeeping Methods
A useful comparison starts with the same transactions and asks where each method places them: on the income statement, balance sheet, or cash flow view, and in which period. For a subscription business, that means examining customer billing dates, service periods, vendor invoices, payment dates, and any amount paid before the service is delivered. It also means separating bookkeeping choices for management reporting from tax treatment, which can depend on a company’s circumstances.
Cypher publicly offers outsourced bookkeeping and accounting for growing businesses. Cypher's current plans include accrual-basis bookkeeping and monthly financial statements. Bookkeeping is an option for founders seeking connected records and recurring financial reporting; confirm current plan details against the official pricing page. This comparison focuses on accounting treatment, not treating a bank deposit as a complete measure of monthly performance.
The Core Difference: Timing is Everything for SaaS Revenue
Cash Basis: When the Money Hits the Bank
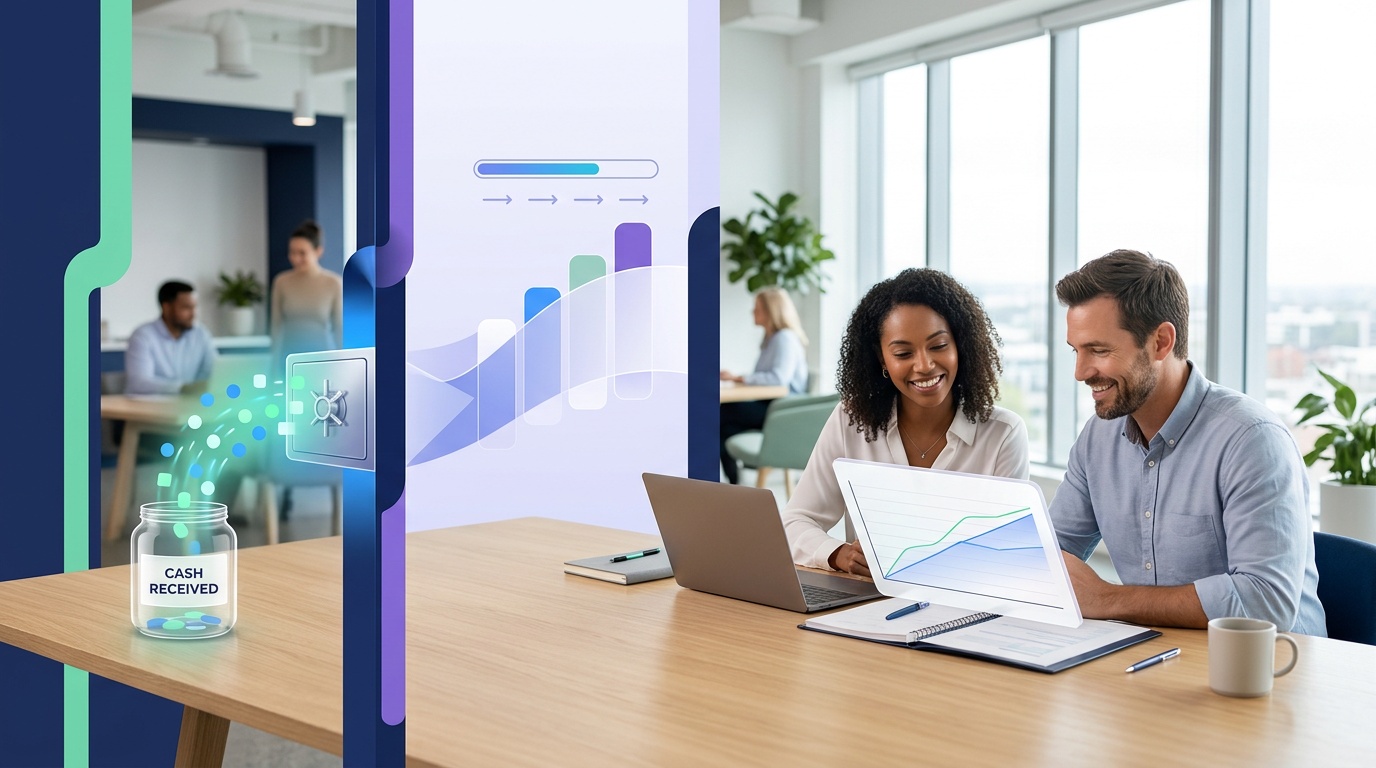
Under cash basis bookkeeping, a customer’s payment is recorded as revenue when the company receives it. A vendor cost is generally recorded when the company pays it. This makes receipts and outflows straightforward to see, but the income statement can bunch activity into payment dates rather than the months in which the company provides its software service.
Accrual Basis: When the Service is Delivered (or Earned)
Under accrual accounting, subscription revenue is recognized over the period the customer receives access to the service, subject to applicable accounting guidance and contract terms. When a customer pays before service is provided, the unearned portion is generally recorded as deferred revenue, a liability on the balance sheet. As the service is delivered, the company recognizes the corresponding revenue. This approach aligns reported activity with the period it relates to.
Illustrating the Timing Difference: A Subscription Example
Consider an illustrative $12,000 annual subscription paid upfront for a year of service. On a cash-basis income statement, the full payment appears as revenue in the month it arrives, with no revenue from that contract in the next 11 months. Under accrual accounting, the company recognizes subscription revenue over the service period, while the part not yet earned remains deferred. The cash arrived at once; the service and related revenue recognition span the year.
| Transaction or view | Cash basis | Accrual basis |
|---|---|---|
| Customer pays annual subscription upfront | Records the receipt as revenue when cash arrives | Records cash received and tracks the unearned amount as deferred revenue |
| Customer receives service during the year | No additional revenue is recorded for the earlier payment | Recognizes revenue as service is delivered over the applicable period |
| Monthly profit and loss statement | Can show a payment-driven revenue spike followed by months without revenue from that contract | Shows revenue in the periods associated with service delivery |
| Balance sheet | Does not provide the same period-by-period deferred revenue view | Shows the unearned portion as a liability until it is recognized |
Impact on Key Financial Statements: P&L and Balance Sheet
The profit and loss statement, also called the income statement, summarizes revenue and expenses for a period. With cash accounting, a large customer prepayment can make one month’s revenue look disconnected from the service delivered in that month. An accrual P&L places revenue in the period it relates to, while the balance sheet shows the remaining customer obligation as deferred revenue. A bank balance and monthly profit can move differently without either number being incorrect: they measure different things.
Expense timing follows the same broad distinction. Cash basis records a cost when paid; accrual basis records it when incurred, with the specific treatment depending on the nature of the cost. When reconciling cash against reported profit, review payment timing alongside accounts receivable, accounts payable, deferred revenue, and prepaid expenses. Keeping those records organized in Bookkeeping supports a clearer monthly view without confusing cash movement with earned revenue.
Why Cash Basis Breaks SaaS Metrics and Investor Confidence
The Illusion of Upfront Payments: Deferred Revenue Explained
An annual prepayment improves cash on hand, but it does not mean the company has delivered a full year of service in the month the payment arrives. Under accrual accounting, the amount related to future service is generally recorded as deferred revenue, a liability, then recognized as the company provides access over the contract term. Without that distinction, a payment-heavy month can look exceptionally profitable while later months appear weak, even when subscriptions remain active.
This gap can frustrate founders comparing the bank balance with the monthly P&L. The balance reflects cash received; the income statement should reflect revenue earned during the period. Reviewing the contract term, billing schedule, service period, deferred revenue balance, and recognized revenue together helps explain both the customer obligation and the company’s performance.
Distorted SaaS Metrics: MRR, ARR, CAC Payback, and LTV:CAC Under Cash Basis
Cash receipts are not a reliable substitute for recurring revenue measures. A customer paying annually can inflate one month’s reported revenue, while a renewal billed later can make another month appear soft. MRR and ARR should be calculated from recurring subscription arrangements using a consistent methodology, not inferred from when customer cash happens to clear. Cash-basis timing can also muddle churn analysis by making billing activity appear to represent changes in active subscriptions.
The same timing problem affects unit economics. If revenue and sales costs land in different periods, CAC payback can look shorter or longer than the underlying customer economics suggest. LTV:CAC comparisons also become harder to interpret when the revenue base shifts with collections rather than service activity. The table shows how the accounting view affects common operating decisions.
| SaaS measure or decision | Cash-basis limitation | Accrual-based view |
|---|---|---|
| MRR and ARR | Payment dates can create spikes unrelated to the monthly subscription run rate | Revenue is reported in periods associated with service delivery, supporting consistent analysis |
| Churn and renewals | Collection timing may not align with a customer’s subscription status | Subscription activity can be reviewed alongside contract and service-period records |
| CAC payback and LTV:CAC | Revenue timing can misalign with sales and acquisition costs | Period-based reporting gives a more coherent basis for evaluating unit economics |
| Investor review | Payment-driven results may require additional reconciliation and explanation | Financial statements can present revenue, obligations, and expenses by reporting period |
Investor Due Diligence Red Flags: Why Cash Basis Isn't Enough
Cash-basis statements may help monitor receipts and payments, but they can leave important questions unanswered during diligence: how much revenue was earned in the period, what customer payments remain unearned, and whether reported margins reflect ongoing operations. Investors may request accrual financials, contract schedules, revenue reconciliations, and supporting balance-sheet detail. If those records are incomplete, the company may need to reconstruct activity before decision-makers can assess performance.
For a SaaS business preparing for outside capital, clean monthly reporting is easier to explain than spreadsheets built after questions arise. Cypher’s Bookkeeping includes accrual-basis bookkeeping and monthly financial statements in its current public plans. Confirm current plan details on the official pricing page.
ASC 606: The Revenue Recognition Standard You Can't Ignore
For companies reporting under U.S. GAAP, ASC 606 provides the framework for recognizing revenue from customer contracts. The central question is not simply when an invoice is paid: it is when the company satisfies its performance obligations under the contract. A SaaS arrangement may involve access to hosted software over time, so the revenue pattern should reflect applicable contract terms and service provided.
Revenue schedules and contract records connect billing, deferred revenue, recognized revenue, and the income statement. Tax accounting can follow different rules from financial reporting, so founders should coordinate tax treatment with qualified tax partners rather than assume one bookkeeping method automatically determines both.
Accrual Accounting: The Foundation for Scaling Your SaaS
Accurate Forecasting and Cash Flow Management
Accrual reporting distinguishes earned revenue from cash collected, while cash-flow reporting shows whether the company can meet upcoming obligations. A forecast can use subscription trends and expected expenses to model operating performance, then map billing and payment timing to anticipated cash needs. This is useful when annual prepayments, monthly payroll, vendor invoices, and renewal dates fall in different periods.
When revenue schedules, accounts receivable, accounts payable, and cash forecasts are connected, leaders can investigate variances earlier. A lower-than-expected bank balance may reflect collection timing, while a revenue change may reflect subscription activity. Separating those drivers makes planning more actionable than treating every movement as a change in business performance.
Operational Efficiency: Matching Expenses to Revenue
Accrual accounting places expenses in the periods to which they relate, subject to the appropriate accounting treatment. This creates a more useful monthly comparison between subscription revenue and costs such as software hosting, payroll, and sales and marketing. A consistent chart of accounts, close schedule, and supporting documentation also reduces the need to rebuild the story from billing exports and manual spreadsheets.
Preparing for Fundraising and Audits
Investors and other stakeholders may ask for financial statements that explain revenue recognition, deferred revenue, operating expenses, and balance-sheet accounts. Accrual records give the company a clearer basis for answering those questions and preparing for diligence or an audit. They do not guarantee investor approval or an audit outcome; they make the underlying financial activity easier to review and support.
Cypher’s Bookkeeping pairs accrual-basis records with monthly financial statements in its current public plans. This can help a growing team maintain a regular reporting cadence and keep financial information organized for management and external review.
Understanding Contract Acquisition Costs and Capitalization (Briefly)
Some costs associated with obtaining a customer contract may require analysis beyond recording the cash payment as an immediate expense. Under U.S. GAAP, the appropriate treatment depends on the nature of the cost, the contract, and applicable guidance; certain qualifying costs may be capitalized and recognized over time. Founders should document the fees and have a qualified accounting professional assess the treatment rather than apply a blanket rule to every sales commission.
Navigating the Transition: When and How to Embrace Accrual
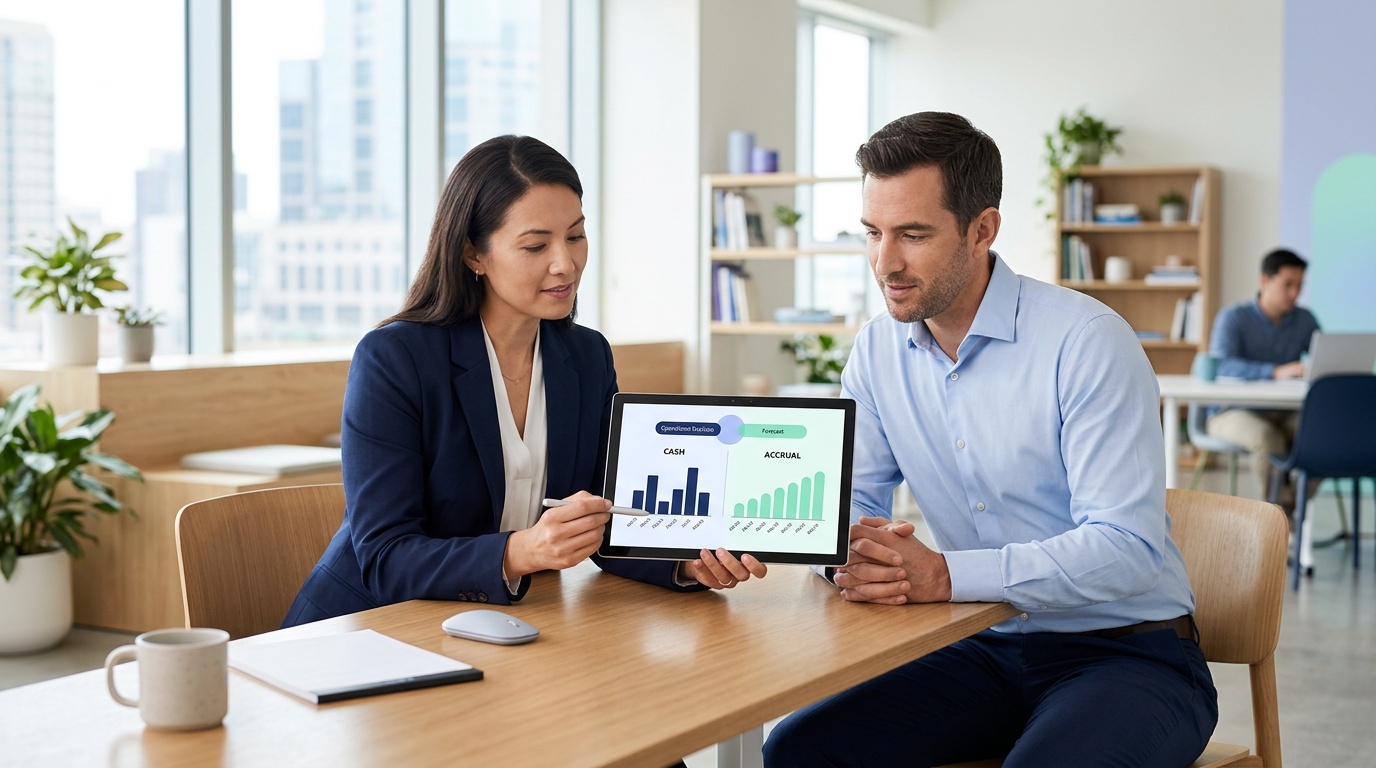
Moving to accrual works best as an operating change, not a last-minute cleanup before fundraising. Timing depends on how you manage subscriptions, expenses, reporting, and external requests. Start by identifying where cash-based records no longer answer practical questions, then build a repeatable close process around billing data, contracts, and supporting documents. Set a clear start date, document open questions, and get qualified accounting guidance on period adjustments or formal accounting-method changes.
Signs Your SaaS Needs to Switch to Accrual
Consider moving to accrual when annual prepayments make monthly results hard to interpret, revenue reports do not match subscription activity, or management cannot explain changes in receivables, payables, and customer obligations. Investor or board reporting needs may also prompt the change. Use this decision checklist to assess readiness:
- Do monthly reports need to reflect service periods, not only payment dates?
- Are deferred revenue and prepaid expenses difficult to track consistently?
- Do billing exports and manual spreadsheets require repeated reconciliation?
- Are stakeholders requesting period-based financial statements or supporting schedules?
If several answers are yes, accrual reporting may give the team a more useful operating view. The decision is about the information the business needs, not a milestone every SaaS company reaches at the same time.
The Dual-Track Approach: Managing Cash and Accrual Simultaneously
Accrual reporting does not replace cash management. Maintain cash forecasts and bank reconciliations for liquidity decisions, while using accrual financial statements to understand activity by period. Keep the underlying transaction records connected, then reconcile the two views through unpaid invoices, customer prepayments, and expenses paid before use. Tax accounting may differ from management or investor reporting, so ask a qualified tax partner whether your filing method is appropriate. Bookkeeping is an option for founders seeking outsourced accrual records and monthly financial statements; confirm current plan scope on Cypher’s pricing page.
Practical Steps for Implementing Accrual Bookkeeping
Choose the first reporting period, review the chart of accounts, and confirm it can capture deferred revenue, prepaid costs, receivables, and payables. Gather customer contracts, billing schedules, vendor invoices, and payment records. Assign owners for recurring reconciliations, set a monthly close calendar, and document how revenue schedules are prepared and reviewed. Start with current-period records, then assess prior periods with an accounting professional instead of assuming every historical entry needs reconstruction. Cypher's current plans include accrual-basis bookkeeping and monthly financial statements through Bookkeeping.
Common Pitfalls to Avoid During Transition
Common trouble spots include changing methods without documenting the effective date, importing incomplete billing data, and treating bank reconciliation as a substitute for revenue schedules. Avoid relying on a spreadsheet with no clear owner or review process. If records have fallen behind, inventory available statements, invoices, contracts, and exports, then agree on a practical catch-up sequence with an accounting professional. A staged transition can make gaps visible while keeping ongoing monthly work manageable.
Frequently Asked Questions
What is the difference between accrual and cash basis accounting?
The difference between accrual and cash basis bookkeeping for a SaaS company comes down to timing. Cash basis records income when payment arrives and expenses when payment is made, while accrual records revenue as it is earned and expenses as they are incurred. Neither changes your bank balance, but each tells a different story about monthly performance.
Is it better to do cash basis or accrual basis?
Accrual basis is usually the better fit for a SaaS company because it shows revenue in the months when service is actually delivered. Cash basis can make a payment-heavy month look unusually profitable, then show little revenue in later months. Many SaaS founders use accrual for performance reporting while still tracking cash closely for liquidity decisions.
Can companies choose between cash basis and accrual basis?
Yes, many companies can choose their bookkeeping method, though eligibility for certain tax treatments depends on factors like business structure, revenue, and jurisdiction. The method you use for management reporting can also be separate from your tax treatment. Confirm what your specific circumstances allow before locking in an approach.
Who should not use accrual accounting?
Very small businesses with straightforward cash transactions and no prepaid or deferred amounts often find cash basis simpler and sufficient. Accrual adds bookkeeping work because it tracks deferred revenue, receivables, and payables. If your revenue does not involve prepayments or service delivered over multiple periods, the extra effort may not pay off yet.
When should I switch my business from cash basis to accrual?
The right time to switch is usually when your revenue model involves prepaid subscriptions, when you need month-over-month performance reporting, or when investors and lenders expect accrual statements. A SaaS company taking annual prepayments benefits early, since cash basis can distort monthly revenue. Plan the transition with your accounting support before a reporting deadline.
How does an annual prepaid subscription look under cash vs accrual bookkeeping?
Under cash basis, a $12,000 annual subscription paid upfront appears as full revenue in the month the payment arrives, with nothing from that contract for the next 11 months. Under accrual, the company recognizes revenue each month across the service period and records the unearned portion as deferred revenue.
What is deferred revenue in SaaS bookkeeping?
Deferred revenue is money a customer has paid before the service has been delivered, and accrual accounting records it as a liability on the balance sheet. As you deliver service each month, you recognize the corresponding revenue. This keeps your P&L aligned with the period the work actually relates to.
